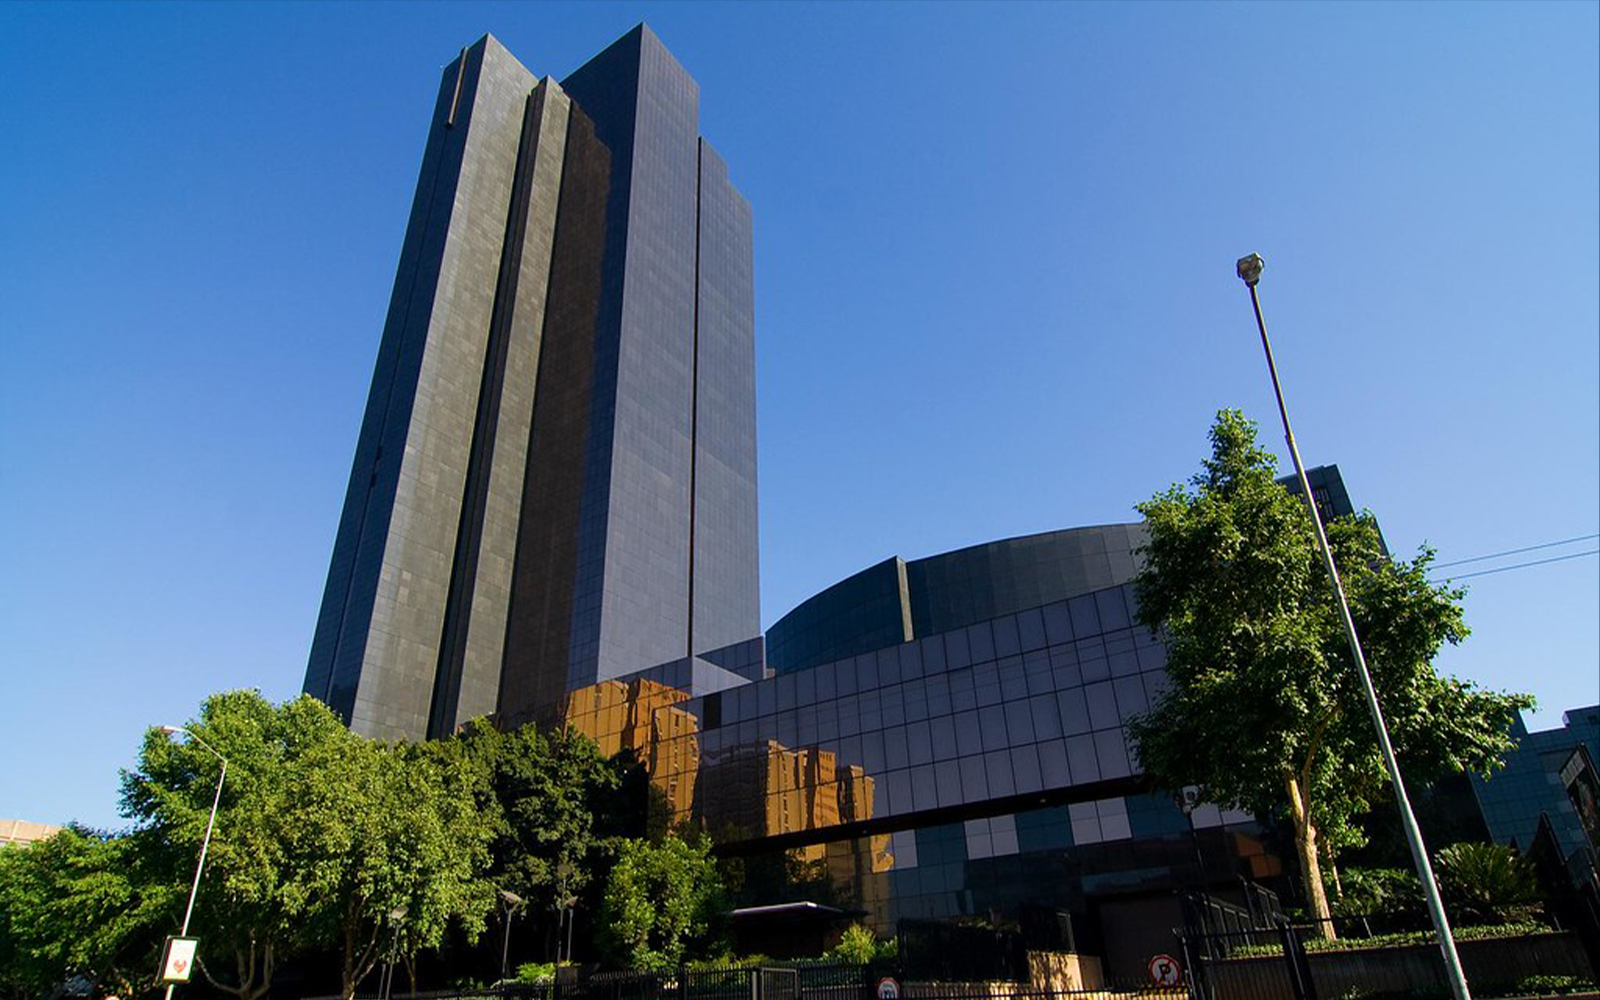
South African households may have been handed a small but important reprieve after May’s inflation numbers came in lower than expected, giving the South African Reserve Bank more space to pause before delivering another interest rate increase.
Headline consumer inflation rose to 4.5% year on year in May, up from 4.0% in April, but the increase was softer than many economists had feared. The number is still uncomfortable, especially for consumers already dealing with higher transport, food and borrowing costs, but it was not the sharp inflation shock that markets had been bracing for. That difference matters, because the Reserve Bank’s next move will depend not only on where inflation is today, but on whether price pressures appear likely to spread deeper into the economy.
The latest inflation print suggests the pressure is real, but not yet runaway. Much of the recent rise has been linked to fuel costs, which were affected by global oil volatility and geopolitical tension. In April, fuel prices delivered one of the largest jumps on record, forcing the Reserve Bank to act early by raising the repo rate to 7%. The concern at the time was that higher fuel prices could move beyond petrol pumps and transport bills, eventually feeding into wages, services, food distribution and general business costs.
May’s numbers have softened that fear slightly. Core inflation, which excludes volatile items such as food and energy, remained more contained, while food prices showed less pressure than expected. That gives policymakers a reason to wait and assess whether the oil shock is temporary rather than immediately tightening policy again. In simple terms, the Reserve Bank may not need to press harder on consumers if inflation is being driven mainly by an external fuel shock rather than broad-based demand in the economy.
For consumers, a pause would be welcome. South Africans are already carrying the weight of high debt-servicing costs, expensive credit, weak disposable income and rising living expenses. Another rate hike would make home loans, vehicle finance, credit cards and business borrowing more expensive. At a time when retail sales growth has already slowed, the danger is that higher rates could further weaken household spending and slow the fragile recovery in domestic demand.
The Reserve Bank, however, is unlikely to declare victory. Inflation is now above the Bank’s 3% target and slightly outside the new tolerance band. Governor Lesetja Kganyago has repeatedly warned that the Bank cannot allow temporary shocks to become permanent expectations. If businesses and households begin to assume that higher inflation is normal, prices and wages can adjust upward in a way that becomes much harder to reverse.
That is why the July interest rate decision remains finely balanced. The softer inflation reading improves the case for a pause, but it does not remove the risks. Oil prices, the rand, food costs, global conflict and local weather conditions could all change the inflation outlook quickly. The Bank’s own forecast still sees headline inflation averaging 4.4% in 2026 before easing to 3.7% next year and returning to the 3% target in 2028.
The key message from the latest data is not that inflation has disappeared. It is that the Reserve Bank now has more room to breathe. Instead of being pushed into another immediate hike, policymakers may be able to hold rates steady, monitor the next round of data and avoid adding unnecessary pressure to consumers and businesses.
For South Africa’s economy, that pause could be significant. It would not solve the cost-of-living crisis overnight, but it would give households breathing space, businesses a more stable planning environment and markets a signal that the inflation threat, while still present, may be easing from its most dangerous point.
Softer Inflation Gives Reserve Bank Room to Hold Fire on Rates